Summary
Paying for independent living without selling your house is achievable when you combine multiple income sources. Explore rental income, home equity access, retirement savings, and veterans benefits to fund your move while keeping your home as an asset.
- Rent your house to generate steady monthly income, with property managers handling tenant issues.
- Access home equity through HELOCs or reverse mortgages (age 62+) to tap built-in wealth without selling.
- Withdraw from IRAs, 401(k)s, pensions, and investments strategically to minimize taxes while funding your move.
- Layer Social Security, rental income, and retirement withdrawals to create stable, diversified payment sources.
- Explore VA pensions, Aid and Attendance benefits, and life insurance options if you're a veteran or have cash-value policies.
Moving to an independent living community doesn’t mean handing over the keys to your house. Many homeowners in Rogers, AR, find that paying for independent living without selling their house is realistic with the right plan. Maybe you want to keep the property as an investment, save it for family, or simply like knowing it’s still yours.
You likely have more choices than you think. Rental income, home equity, retirement savings, and benefits you’ve already earned can all play a part in affording senior living while you keep your home.
Use Rental Income to Cover Monthly Community Costs
Renting out your house can bring in steady income to put toward community fees. Rogers sits in a fast-growing region near Bentonville, Springdale, and Fayetteville, so plenty of people are regularly looking for homes to rent.
If being a landlord isn’t how you want to spend your days, a property management company can screen tenants, handle maintenance requests, and collect rent for you for an additional fee. This approach can offer several advantages:
- Keeps your home equity in place for future needs or inheritance.
- Provides ongoing monthly income to offset community costs.
- Preserves the property as a potential asset for family members.
- Hands day-to-day landlord tasks to a professional manager.
Access Home Equity While Keeping Ownership
Your home equity is wealth you’ve built over the years, and you can access some of it without selling. A home equity line of credit (HELOC) lets you draw money as needed, making it a useful backup for occasional expenses. Some lenders set different terms once a home becomes a rental, so it may help to apply before you move.
Reverse mortgages, available to homeowners 62 and older, are a different story. The loan can come due if you live away from the home for more than six months for non-medical reasons and no co-borrower lives there. That rules them out for most moves unless a spouse or co-borrower is staying in the house. A financial advisor or HUD-approved counselor can help you compare financing for independent living options.
Use Retirement Accounts & Investments
Retirement savings and investments can fund community living while the house stays in your name. This works especially well if your home is paid off. Common funding sources include:
- IRA distributions and 401(k) withdrawals.
- Pension income and annuity payments.
- Investment dividends and interest income.
- Proceeds from planned stock or bond sales.
A financial planner can map out withdrawals to limit your tax bill and help your savings last longer.
Consider Bridge Loans for Short-Term Needs
If you expect to sell eventually but aren’t ready yet, a bridge loan can cover early community costs while you prepare the house or wait for a better market. It’s one of the senior living payment alternatives that lets you move into your new apartment home right away. Bridge loans usually carry short terms and higher interest rates, so ask about costs up front.
Without a rushed sale hanging over you, you can settle in, enjoy three chef-prepared meals each day, and meet your neighbors at your own pace. Once the house sells, you pay off the loan and keep the remaining proceeds.
Combine Multiple Income Sources
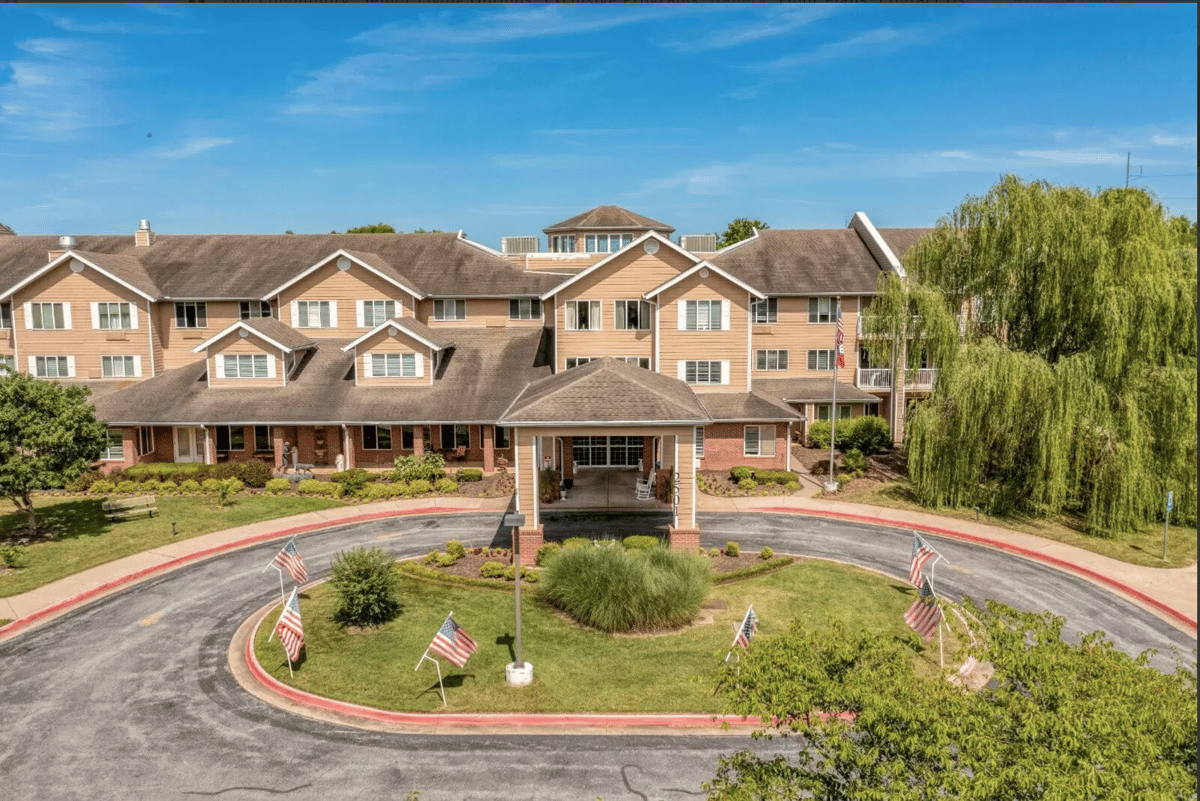
Most residents pay for independent living with several income streams. Social Security often serves as the base, with pension payments, retirement withdrawals, investment income, and rent from your house layered on top. If one source dips for a while, the others keep monthly payments steady. Reviewing floor plans and pricing at Morada Rogers gives you a real number to plan around.
Keeping your house while moving to a community this way feels more secure than relying on one large home sale. Independent Living with supportive services** at Morada Rogers includes housekeeping and complimentary scheduled transportation, leaving more time for concerts at Railyard Park or an afternoon in Downtown Rogers.
Our Independent Living with supportive services** community is designed to support your independence while offering access to additional help—only when and if you want it. A choice of third-party providers is available onsite for your convenience, but you are under no obligation to use any particular one. This flexible approach is perfect for individuals or couples with varied needs. Extend your independent lifestyle by choosing to make our community your home.
Explore Veterans Benefits & Insurance Options
Wartime veterans and surviving spouses may qualify for a VA pension, which has income and net worth limits. Those who meet additional requirements may receive higher monthly payments through VA Aid and Attendance or Housebound benefits. If you’re still working out how to afford independent living, an accredited veterans service officer can help check your eligibility. Morada Rogers also offers a Veterans Program with exclusive savings for those who served.
A life insurance policy with cash value may be another resource. You may be able to borrow against it, take a partial withdrawal, or sell it through a life settlement. Each choice changes what your family receives later, so talk with your agent or financial advisor first.
Plan Your Move to Morada Rogers
Keeping your house and moving to senior living can work together with the right mix of resources. We’re happy to answer your questions about costs and Independent Living with supportive services** in Rogers, AR. Schedule a personalized tour of Morada Rogers to see our community for yourself.
A choice of third-party providers is available onsite for convenience, but residents are under no obligation to use any particular one.